First Time Buyer Guide: Securing a Mortgage for Melbourne Houses in 2026
Melbourne house hunting has its own rhythm: Saturday auctions, open inspections squeezed into fifteen-minute windows and suburbs where a short tram ride changes the price conversation completely. For first-home buyers, the paperwork…
2 min
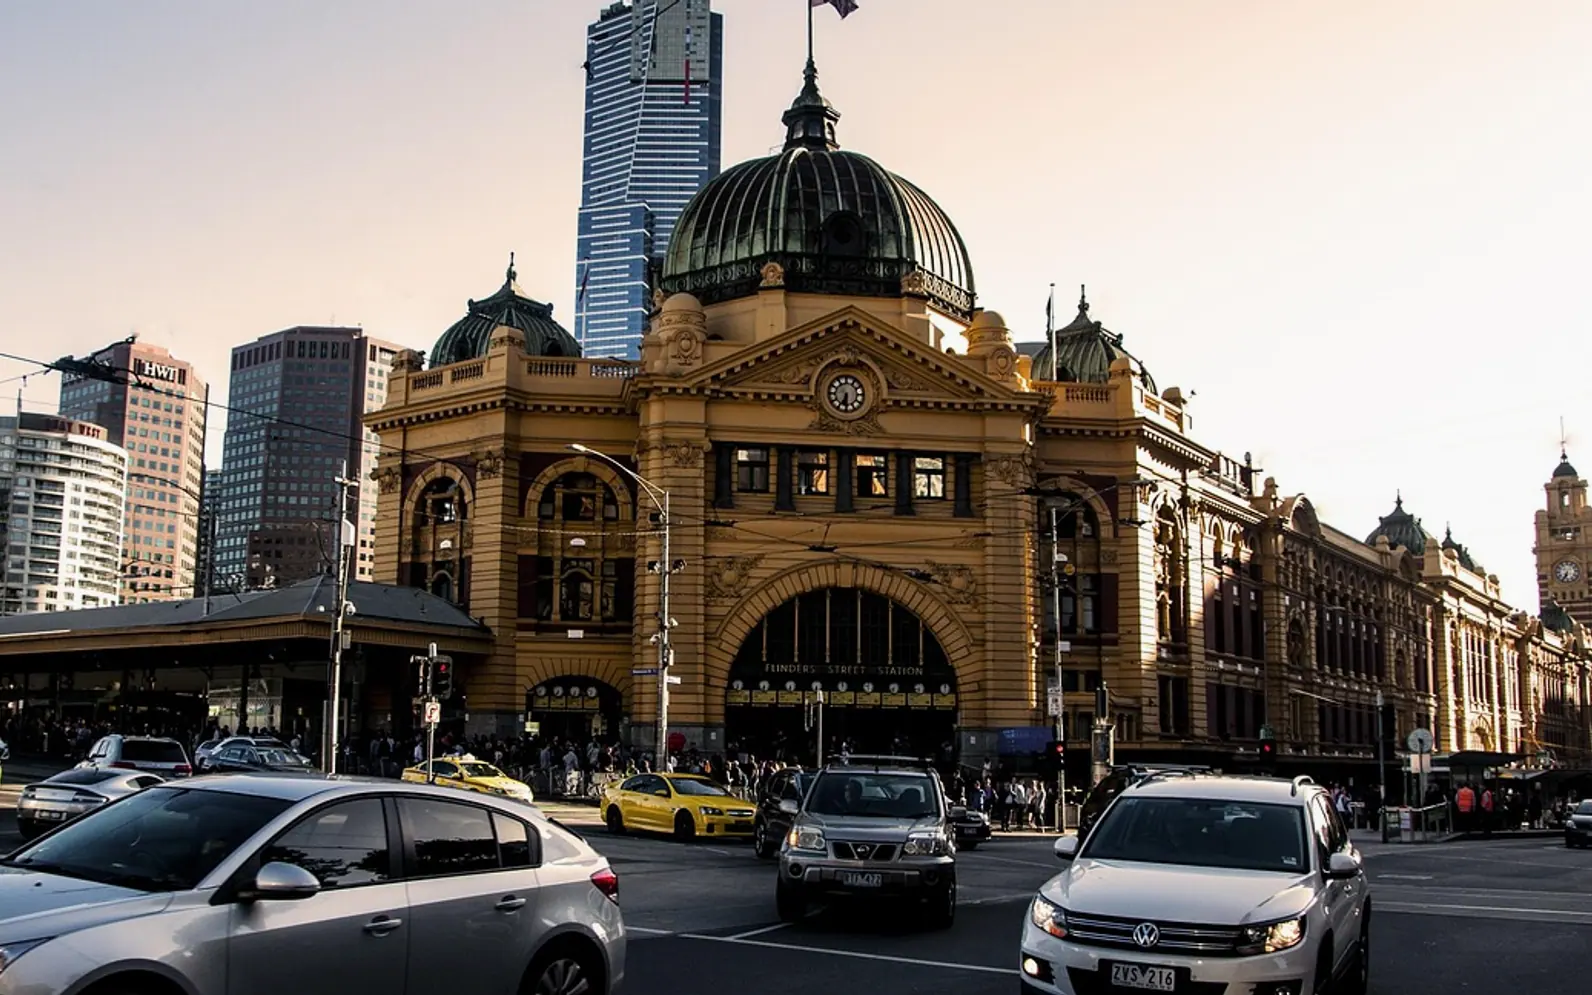
Melbourne house hunting has its own rhythm: Saturday auctions, open inspections squeezed into fifteen-minute windows and suburbs where a short tram ride changes the price conversation completely. For first-home buyers, the paperwork side matters just as much as the weekend inspections. Lenders want to see a clear, steady financial picture, and preparing that picture early makes every later step calmer.
Step one: know the full cost of buying
The deposit is only part of the money needed. Stamp duty, legal and conveyancing fees, building and pest inspections, loan establishment costs and moving expenses all arrive around settlement. Victoria offers concessions and grants for some first-home buyers, but eligibility depends on price, property type and personal circumstances, so the current rules should be checked with the state revenue office before relying on them.
A smaller deposit can still work with some lenders, though it may involve lenders mortgage insurance, which adds to the cost.
Step two: tidy the financial file
- Pay down or close credit cards and buy-now-pay-later accounts that are not needed; lenders consider limits, not just balances.
- Show stable income: recent payslips for employees, tax returns and financial statements for the self-employed.
- Keep bank statements clean and regular for the months before applying.
- Request a free copy of the credit report and correct any errors.
Step three: test the repayments, not just the rate
Interest rates can move during the life of a loan. Before choosing a price range, calculate repayments at a rate noticeably higher than today's and check that the household budget still works, including childcare, transport and the cost of running a house rather than a flat. Fixed, variable and split loans each balance certainty against flexibility in different ways, and offset accounts or redraw facilities may suit some buyers more than others.
Step four: lenders, pre-approval and settlement
Lenders treat casual income, bonuses, contract work and existing debts differently, so the same buyer can receive quite different borrowing limits. A broker can compare policies across many lenders at once. Melbourne buyers, for instance, can find Blutin Finance Mortgage Broker listed with directions and opening details on Google Maps, which makes arranging a first conversation straightforward.
Conditional pre-approval then gives a working budget for auctions and private sales. It is not a final loan approval, and the specific property will still be assessed.
From offer to keys
- Have a conveyancer or solicitor review the contract and vendor statement before signing or bidding.
- Arrange building and pest inspections where possible.
- Remember that auction purchases are usually unconditional, so finance must be ready beforehand.
- Arrange insurance from the date the property becomes the buyer's risk.
- Avoid new debts or job changes until the loan has settled.
Keeping the risk in view
A mortgage is a long commitment, and property prices can drop as well as climb. Repayments may increase, and circumstances such as illness or job loss can strain any budget. This article gives general information only; before committing, buyers should seek independent financial and legal advice that considers their own situation.
Desk habits
Small routines that save time later
Picked up while writing the notes on this site.
Photograph the meter
A dated photo settles most arguments about estimated readings.
Name files by date
Year, month, day at the start of a filename keeps invoices and letters in order.
Sketch before you measure
A rough floor plan stops you missing an alcove or counting a strip twice.
Update the router
Check for firmware updates whenever you change your Wi-Fi password.
Put terms in writing
A short email confirming price and due date beats any verbal promise.